by Hotel Development Guide – Darren Blanchard
Last Updated: October 2026
Hotel management fees define how a hotel operator is paid for managing an owner’s asset. They generally combine a base fee linked to revenue with an incentive fee linked to a contract-defined measure of operating profit. Alongside these sit system charges, reimbursable expenses, and development or pre-opening fees, which together determine the wider cost of the operator relationship.
For developers and investors, the commercial question extends beyond whether a base fee is 2.5% or 3.0%, or an incentive fee is 8% or 10%. The revenue included, deductions permitted, payment thresholds, and interaction with other charges can matter as much as the headline percentages. A lower quoted rate does not necessarily produce a better outcome for the owner.
There is no single fee structure suitable for every hotel. Brand positioning, operating complexity, market conditions, and negotiating strength all shape the hotel management agreement. This guide examines the principal fee components, their interaction, and the practical questions owners should ask when comparing proposals and negotiating commercial terms.
Fee structures also influence how risk and reward are shared. A revenue-based fee remains payable during periods of weak profitability, while an incentive fee depends on the agreed profit calculation and payment conditions. Understanding that distinction is essential when assessing cash flow during opening, stabilisation, and more difficult trading periods.
Summary Table of Hotel Management Fees
The following table summarises the principal fees and charges encountered in hotel operator arrangements. The indicative ranges draw on the author’s professional experience and published industry commentary; they are broad reference points rather than the results of a current market survey. Actual terms vary with the operator, brand, geography, property characteristics, negotiation date, and calculation basis. Percentages should therefore be assessed alongside their revenue or profit definitions, payment conditions, and associated charges when comparing proposals.
| Fee Type | Description | Typical Basis | Indicative Range | Key Considerations |
|---|---|---|---|---|
| Base Fee | Core fee for management services and brand support, payable regardless of profitability | % of Total Hotel Revenue (net of VAT) | 2.0% – 4.0% | Revenue-linked charge payable regardless of profitability; definition of revenue is critical. |
| Incentive Fee | Performance-based fee linked to profitability of the hotel | % of GOP or AGOP (often scaled) | 5.0% – 15.0% | Alignment tool; structure and thresholds significantly affect outcomes |
| Reservation Fees | Charges for use of operator’s central reservation systems and distribution platforms | Per booking or % of room revenue | Varies widely | Linked to brand distribution strength; can be material in high-volume systems |
| Marketing Contribution | Contribution to centralised brand marketing, sales and distribution activities | % of room revenue | 1.0% – 3.0% (indicative) | System-wide and often non-negotiable; benefits may not be directly measurable |
| Loyalty Programme Costs | Costs associated with participation in brand loyalty schemes | Per stay, per point, or % of revenue | Variable | Can be significant depending on brand penetration and guest mix |
| IT / Systems Fees | Charges for centralised IT infrastructure, software and support systems | Fixed or variable | Variable | Increasingly important as systems evolve; often subject to change over time |
| Training & Quality Assurance | Costs related to staff training, audits and brand compliance programmes | Fixed or periodic charges | Variable | Supports brand standards; may increase with new initiatives |
| Reimbursable Expenses | Pass-through costs for services provided by operator or third parties | As specified in the agreement, check allocation and any markup. | Variable | Requires transparency; allocation methodology should be understood |
| Technical Services Fees | Fees for design, development and construction phase support | Fixed, per room, or % of development cost | Project-specific | Paid pre-opening; can be material; scope and overlap should be understood |
| Pre-Opening Fees | Costs associated with preparing the hotel for opening, including staffing and systems setup | Fixed or budget-based | Project-specific | One-off |
- Overview of Hotel Management Fee Structures
- Base Fee
- Incentive Fee
- How to Calculate Hotel Management Fees: A Worked Example
- The Relationship Between Base and Incentive Fees
- Additional Operator Charges
- Technical Services and Development-Related Fees
- Hidden and Overlooked Costs
- Fee Structuring Strategies (Owner Perspective)
- How Operators Evaluate Fees
- Common Mistakes When Negotiating Hotel Management Fees
- Evaluating Hotel Management Fees as an Owner
- Illustrative Fee Clauses and Drafting Considerations
- Closing Note
Overview of Hotel Management Fee Structures
An operator’s fee model typically comprises three distinct layers: core compensation fees, system-related charges, and reimbursable expenses. Together, these elements form the total cost of engaging a hotel operator and must be assessed collectively rather than in isolation.
Operator Compensation Fees
The core of the fee structure is the operator’s compensation, which consists primarily of the base fee and the incentive fee. These two components represent the operator’s principal economic participation in the hotel and are designed to balance stability with performance.
The base fee provides a relatively predictable income stream tied to revenue, ensuring the operator is compensated for management services and brand support, regardless of profitability. The incentive fee, by contrast, is linked to operating performance, typically measured at the level of Gross Operating Profit (GOP) or Adjusted Gross Operating Profit (AGOP).
From the operator’s perspective, the absolute combined value of these two fees, particularly in a stabilised year, is a primary determinant of whether a project is commercially attractive. Internally, operators often assess projects based on projected fee income over time rather than on individual fee percentages, reinforcing the importance of evaluating the structure as a whole.
In practice, operators will also consider the stabilised fee income in absolute monetary terms, not just as a percentage of revenue or profit, and this figure often acts as a minimum gatekeeper threshold when deciding whether to pursue a project. Depending on the brand, positioning and strategic priorities, this minimum level can vary significantly.
System and Service Charges
In addition to core compensation, operators levy a range of system-related charges that support the broader brand and distribution ecosystem. These typically include reservation fees, marketing contributions and distribution-related costs.
Reservation fees are generally linked to bookings generated through the operator’s central systems and are often charged either per reservation or as a percentage of room revenue. Marketing contributions fund global and regional sales efforts, brand campaigns, loyalty programmes and digital platforms. These contributions are usually pooled across the operator’s network, meaning individual hotels benefit from collective brand investment.
While these charges are often presented as standard or non-negotiable, their cumulative impact can be significant. In some cases, they may rival or even exceed the base fee in terms of total cost, particularly in highly branded, distribution-driven environments.
Reimbursable Expenses
The third layer consists of reimbursable expenses, which cover services provided either centrally or directly to the hotel. These can include IT systems, accounting support, training programmes, quality assurance audits and guest satisfaction platforms.
Although these costs are typically passed through without markup, they are not always insignificant. The scope, frequency, and allocation methodology of these expenses can vary widely between operators and, in some cases, may lack transparency. As a result, they require careful review during the negotiation process.
The fee structure outlined above applies to the hotel’s ongoing operations; operators are also involved during the development and pre-opening phases of a project. These activities are typically compensated through separate fee arrangements, which sit outside the core operating fee structure but form an important part of the overall economic relationship.
Development & Pre-Opening Fees
While base and incentive fees form the core of operator compensation, they do not represent the full economic relationship between owner and operator. Additional fees, most notably technical services fees and pre-opening services, are typically charged separately and relate to the development and implementation of the hotel rather than its ongoing operation. These costs can be material and should be considered alongside the operational fee structure when evaluating the overall commercial framework.
Base Fee
Definition and Economic Role
The base fee is generally considered the fundamental component of the operator’s compensation. It is typically calculated as a percentage of total hotel revenue, usually net of VAT, and is intended to cover the cost of providing management services, brand affiliation and operational support.
Drawing on the author’s professional experience, base management fees of approximately 2.0% to 4.0% of defined hotel revenue provide a broad indicative reference range, although individual proposals may fall outside it. The agreed percentage depends on the operator, brand, property characteristics, market conditions, and negotiating position. Owners should assess the rate alongside the contractual revenue definition, opening-period concessions, any minimum fee provisions, and additional operator charges, since these determine the overall commercial effect.
From the operator’s perspective, the base fee represents a relatively secure and predictable income stream. Because it is linked to revenue rather than profitability, it provides a degree of protection against operational volatility. Even in periods of reduced profitability, the operator continues to receive compensation, reflecting the ongoing provision of services.
For the owner, however, the base fee is a revenue-linked charge that generally remains payable regardless of profitability. Although its amount rises or falls with the revenue on which it is calculated, it does not depend on the hotel generating sufficient profit to cover debt service or deliver the expected return. This distinction matters particularly during the opening and stabilisation period, or when trading conditions weaken: the operator may continue to earn a base fee while the owner’s remaining cash flow is under pressure. The fee should therefore be assessed against projected revenue, operating margins, financing obligations, and the other charges payable under the agreement.
Key Commercial Considerations
One of the most important aspects of the base fee is how total hotel revenue is defined. In straightforward single-use hotels, this may be relatively simple. However, in mixed-use developments or assets with third-party components, such as retail, residential or leased outlets, the definition becomes more complex.
If revenue streams are not clearly defined and appropriately excluded where necessary, owners may find themselves paying fees on income that is not directly linked to the operator’s management responsibilities. This makes the precise drafting of revenue definitions a critical element of the HMA.
Another important consideration is the relationship between base and incentive fees. Operators may agree to a lower revenue-based fee in exchange for a higher profit-based incentive fee, changing how their remuneration responds to the hotel’s performance. For the owner, the effect depends on the agreed profit definition, payment thresholds, and other charges, rather than on the percentages alone. Both structures should therefore be tested against the same opening, stabilised, and downside trading assumptions to understand their impact on operator remuneration and the cash remaining for the owner.
Ramp-up provisions are also common, particularly in new developments. During the initial years, as the hotel establishes its market position, operators may agree to reduced base fees to support cash flow. These reductions are often offset by higher fees once the hotel reaches stabilisation, reflecting the long-term nature of the agreement.
For example, a base fee that stabilises at 3.0% of total revenue may be structured at 1.5% in year one, 2.0% in year two and 2.5% in year three, before reaching the full 3.0% from year four onwards. In some cases, the operator may seek to recover part of this early-year concession through a slightly higher stabilised fee or through an enhanced incentive fee structure.
Negotiation Dynamics
Despite its importance to owners, the base fee is often one of the more difficult components to negotiate. Operators typically view it as the minimum level of compensation required to deliver their services and may resist significant reductions.
In some cases, owners may seek to subordinate the base fee to debt service or owner priority returns. While theoretically attractive, such provisions are rarely accepted by operators without corresponding concessions elsewhere in the agreement.
Ultimately, the negotiation of the base fee is less about achieving the lowest possible percentage and more about ensuring that it is appropriately balanced within the overall fee structure.
Incentive Fee
Purpose and Alignment
The incentive fee is designed to align the operator’s interests with the hotel’s financial performance. Unlike the base fee, it is contingent on profitability and therefore directly linked to the operation’s success.
Incentive fees are commonly expressed as a percentage of GOP or a contract-defined adjusted profit measure. The 5.0% to 15.0% range used in this guide is an indicative reference drawn from the author’s professional experience and general industry reading, rather than a universal standard or the result of a current market survey. Individual arrangements may fall outside this range, and the percentages are not directly comparable without examining the calculation base, permitted deductions, performance thresholds, and any owner’s priority return. In scaled structures, the distinction between whole-base rates and marginal bands can materially change the resulting fee, as illustrated below.
From an owner’s perspective, an incentive fee can help align operator remuneration with operating performance, but the strength of that alignment depends on the profit definition and payment conditions agreed in the contract. A fee calculated on a positive operating profit may still become payable when insufficient cash remains to meet debt service, fund capital requirements, or deliver the owner’s expected return. Any owner’s priority return or other payment threshold must therefore be considered alongside the incentive percentage. For the operator, the structure provides an opportunity to participate in improved performance, while the owner must assess whether the resulting allocation of cash supports the investment’s wider objectives.
Structures and Variations
Incentive fee structures can vary significantly in complexity. A fixed percentage structure is the simplest, applying a single rate to the chosen profit metric. While straightforward, it may not fully capture performance variations.
A sliding-scale incentive fee links the applicable fee rate to defined performance thresholds, such as GOP margin. However, the term “sliding scale” does not, by itself, explain how the fee is calculated. Two approaches should be distinguished: a whole-base structure, where the achieved performance level determines a rate applied to the entire agreed profit base, and a marginal-band structure, where different rates apply to successive portions of that base. These approaches can produce materially different fees from identical headline percentages, so an operator proposal should specify the calculation method rather than relying on the description “scaled” or “tiered.”
| Calculation method | How the fee operates |
|---|---|
| Whole-base rate | The achieved performance level determines a single percentage, which applies to the entire agreed profit base. Crossing a threshold can therefore increase the fee on all qualifying profit, including profit below that threshold. |
| Marginal bands | Each percentage applies only to the portion of the agreed profit base falling within its defined band. Crossing a threshold subjects the additional portion to the higher rate, while the lower portions retain their respective rates. |
For example, assume hotel revenue of €5 million and GOP before the incentive fee of €2.1 million, giving a GOP margin of 42%. For illustration, the fee schedule specifies 0% below a 20% margin, 7% from a 20% margin up to and including 40%, and 10% above 40%. The following comparison uses GOP as the calculation base, with no further adjustments or owner priority return.
| Calculation method | Calculation using the illustrative schedule | Incentive fee |
|---|---|---|
| Whole-base rate | The 42% GOP margin places the hotel in the 10% tier. That rate applies to the entire €2,100,000 GOP. | €210,000 |
| Marginal bands | The first €1,000,000 of GOP attracts no fee; the next €1,000,000 attracts 7%; and the remaining €100,000 attracts 10%. | €80,000 |
Where an operator’s template uses the whole-base approach, the commercial rationale may be that each performance threshold represents a target: achieving that target qualifies the operator for a higher percentage of the entire agreed profit base. Operators typically favour this approach for its apparent simplicity, arguing that calculating fees across separate marginal bands adds complexity to budgeting, reporting, and reconciliation. From the owner’s perspective, however, ease of calculation should be assessed alongside the financial effect of crossing each threshold, particularly where a small improvement in operating performance triggers a higher rate on all qualifying profit.
This creates a potential threshold effect in which the incentive fee increase exceeds the additional operating profit generated, leaving the owner with less profit after the fee despite improved hotel performance. Using the illustrative whole-base schedule above, GOP of €1,995,000 on revenue of €5 million produces a 39.9% margin and a 7% incentive fee of €139,650, leaving €1,855,350 after that fee. If GOP increases by €10,000 to €2,005,000, the margin reaches 40.1%, triggering a 10% fee of €200,500 and leaving €1,804,500.
The additional €10,000 of GOP therefore increases the fee by €60,850 and reduces the owner’s profit after the incentive fee by €50,850. Comparing margins just below and just above 40% illustrates the effect without relying on how the agreement treats exactly 40%; the applicable boundary and any rounding provisions should be checked in the contract.
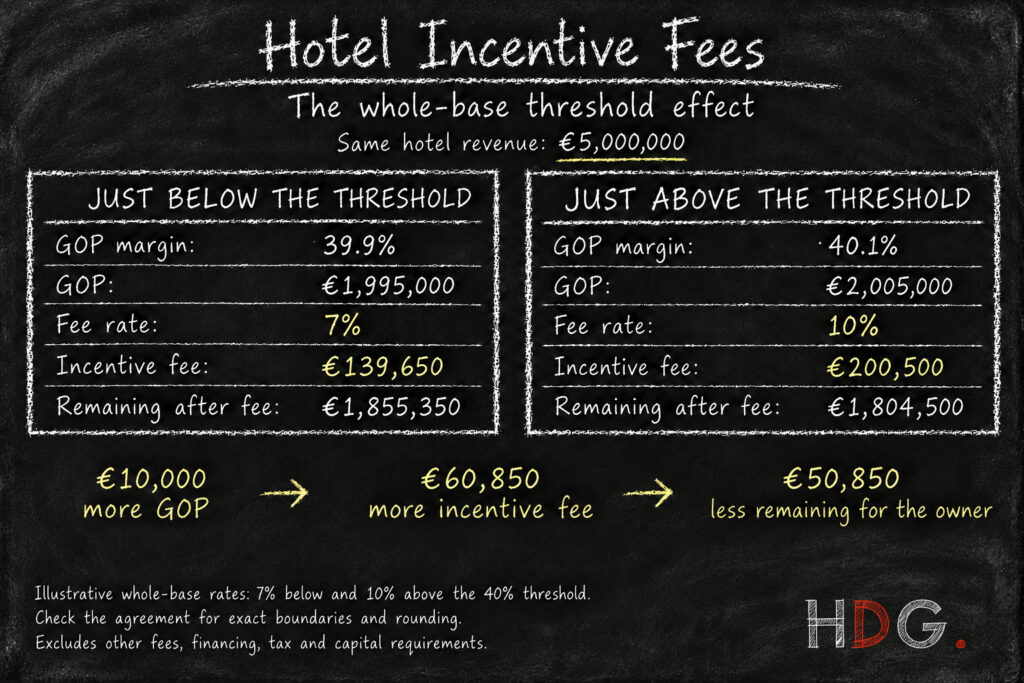
This simplified example excludes other fees and owner obligations, but demonstrates why proposed fee structures should be tested immediately below, at, and above each threshold.
A further complication is the timing of the final profit calculation. Where incentive fees are provisionally calculated or paid using management accounts, the applicable performance band may remain uncertain until the annual accounts are finalised and, where required, audited, potentially well into the following financial year. Year-end adjustments may move the hotel above or below a threshold, changing both the final fee entitlement and the balance payable or recoverable.
This is particularly significant under a whole-base structure, where a relatively small adjustment to reported profit can change the percentage applied to the entire annual profit base. The agreement should therefore clearly establish the basis for provisional calculations, whether thresholds are assessed annually or otherwise, the treatment of audit adjustments, and the timing and mechanism for reconciling underpayments or overpayments.
Owner’s priority return structures introduce an additional layer of protection by requiring a minimum level of cash flow to be achieved before any incentive fee is paid. While common in North America, these structures are less prevalent in emerging markets but are increasingly seen in more mature European transactions.
GOP vs AGOP
The choice between GOP and AGOP is one of the most technically significant aspects of incentive fee design. GOP represents operating profit before fixed charges, while AGOP introduces adjustments for certain costs, which may include base fees, capital reserves or other items.
AGOP adjusts GOP using the deductions specified in the agreement, so its usefulness depends on what those adjustments capture and the purpose of the calculation. The label alone does not establish how closely the measure reflects the cash available to the owner. A clear assessment therefore requires identifying each permitted deduction, understanding its treatment, and testing its effect on the incentive fee. Differences between the owner’s investment objectives and the operator’s management responsibilities can make these definitions an important part of commercial negotiations, particularly when considering costs that the operator does not directly control.
In practice, there is no standard definition (AGOP is not formally standardised within USALI), and discussions typically centre on a number of commonly disputed items, including the treatment of FF&E reserves, property insurance, property taxes, ground rent or lease payments, capital expenditure, and, in principle, financing-related costs (even where these are ultimately excluded). At the heart of these debates is the question of control: operators generally argue that only costs within their direct operational influence should be deducted, while owners seek to reflect the full economic burden of owning the asset.
The treatment of the FF&E reserve is particularly contentious. From the owner’s perspective, it represents a recurring and unavoidable cash outflow required to maintain the asset and preserve brand standards, and therefore should be deducted before any incentive fee is paid. Operators, by contrast, typically view the FF&E reserve as a capital reinvestment decision rather than an operating cost, and therefore argue that it should sit below the incentive calculation. The final position is usually a negotiated compromise, but even small differences in how these items are treated can have a material impact on the level and timing of incentive fee payments.
For this reason, clarity in drafting is essential. Ambiguity in AGOP definitions can lead to disagreements or unforeseen concessions during operation, particularly in periods of financial stress.
Practical Considerations
Although it is possible to design highly sophisticated incentive structures, simplicity is often preferable. Incentive schemes must be clearly understood by both parties and, importantly, by the hotel’s management team.
If the structure is overly complex or perceived as unattainable, it can undermine motivation rather than enhance it. An effective incentive fee should be achievable, transparent and directly linked to operational performance.
How to Calculate Hotel Management Fees: A Worked Example
Consider a hotel with annual revenue of €5 million and operating profit before management fees of €1.5 million. For this illustration, the agreement specifies a base fee of 3% of revenue and an incentive fee of 10% of the profit remaining after deducting the base fee. These are hypothetical terms chosen to demonstrate the calculation; they are not market benchmarks or recommended commercial terms.
| Item | Calculation | Amount |
|---|---|---|
| Base management fee | €5,000,000 × 3% | €150,000 |
| Incentive fee calculation base | €1,500,000 − €150,000 | €1,350,000 |
| Incentive management fee | €1,350,000 × 10% | €135,000 |
| Combined management fees | €150,000 + €135,000 | €285,000 |
| Profit remaining after both fees | €1,500,000 − €285,000 | €1,215,000 |
The combined management fees represent 5.7% of hotel revenue in this example. Adding the headline rates of 3% and 10% would give a misleading result because the percentages apply to different calculation bases. The remaining €1,215,000 is the balance after these two fees alone, rather than the owner’s distributable cash flow: additional operator charges, capital requirements, financing costs, tax, and other obligations have been excluded. Actual agreements may also apply different profit adjustments, owner priority returns, thresholds, or payment conditions.
The Relationship Between Base and Incentive Fees
The relationship between base and incentive fees is one of the most critical aspects of fee structuring. These components are not independent; they represent different approaches to allocating risk and reward between the owner and the operator.
A higher revenue-based fee gives the operator remuneration that is less directly dependent on profitability, while increasing the charges the owner must meet during weaker trading periods. Reducing that fee in exchange for a higher incentive fee changes how remuneration responds to performance, but does not automatically improve the owner’s cash flow or ability to service debt. The outcome depends on the agreed profit definition, incentive rates, thresholds, and additional charges. Owners should therefore compare alternative structures using the same opening, stabilised, and downside assumptions, examining both total operator remuneration and the cash remaining to meet financing obligations, capital requirements, and investor returns.
However, this shift also transfers risk to the operator, who may be less willing to accept reduced base fees without a credible path to achieving incentive income. The final structure is therefore a negotiated balance that reflects market conditions, asset characteristics and the relative bargaining power of the parties.
Additional Operator Charges
Beyond base and incentive fees, operators apply a range of additional charges that can materially affect the hotel’s overall cost structure. These operator charges are typically applied on a system-wide basis and are therefore often presented as non-negotiable; however, they must be fully understood, clearly explained and transparently detailed. As a matter of good practice, owners should request a comprehensive schedule of all additional operator charges at an early stage in negotiations to ensure that the full cost of operator engagement is properly assessed.
Reservation fees are typically linked to bookings generated through the operator’s systems and may be charged per reservation or as a percentage of room revenue. These fees are closely tied to the strength of the operator’s distribution platform and can be a significant cost for highly network-driven brands.
Marketing contributions are generally structured as a percentage of room revenue and fund centralised branding, sales and promotional activities. While these contributions provide access to global marketing resources, their direct impact on individual hotel performance is not always transparent.
Other charges may include loyalty programme costs, IT systems, training programmes and brand compliance initiatives. While individually modest, these costs can add up and should be considered part of the overall fee structure. In practice, these charges are not static and tend to evolve over time as operators update their branding, technology platforms and human resource programmes.
While the operator’s development team should be able to provide a current schedule of applicable charges, the agreement itself may not fully capture how these costs develop over the life of the contract, effectively creating a degree of open-ended exposure for the owner. This can become a point of contention, particularly where new systems or brand initiatives are introduced. As a result, it is advisable to address these charges holistically during negotiations, including caps on total additional charges, a clear distinction between mandatory and optional costs, and the extent to which the owner retains control or approval rights over such expenditures.
Technical Services and Development-Related Fees
Nature and Timing of Technical Services Fees
Technical Services Fees (TSF) are typically charged by the operator during the design, development and construction phases of a hotel project. Unlike base and incentive fees, which relate to ongoing operations, these fees compensate the operator for providing technical input into the asset’s planning and execution. This usually includes services such as:
- Concept and design review
- Brand standard implementation
- Architectural and engineering coordination
- Operator input into layout efficiency and back-of-house planning
- Procurement guidance and FF&E input
These services are critical to ensuring that the hotel is developed in line with brand standards and operational requirements, reducing the risk of costly redesign or inefficiencies once the hotel is operational.
Fee Structures and Commercial Impact
Technical services fees are typically structured either as:
- A fixed fee
- A percentage of total development cost
- A per-room fee
Depending on the scale and complexity of the project, these fees can be substantial and should be factored into the overall development budget from an early stage. From an owner’s perspective, TSF is often perceived as an additional cost layer, particularly as it is incurred before the hotel generates any revenue. However, from the operator’s perspective, it reflects the deployment of specialised technical teams and brand resources during the development phase.
Overlap and Coordination Considerations
Technical services input from the operator should be viewed primarily as a supporting function within the wider development team, rather than as a standalone or competing consultancy role. While there may inevitably be some overlap with architects, designers, project managers and cost consultants, this is typically a function of the operator’s role in ensuring that brand standards and operational requirements are fully integrated into the design and delivery of the asset.
In many cases, the operator’s technical services input can be one of the most valuable contributions during the development phase. Unlike other consultants, whose involvement is often limited to specific stages of the project, the operator remains engaged through pre-opening, commissioning and into ongoing operations. This continuity allows the operator to provide practical, experience-based input that bridges the gap between design intent and operational reality.
For this reason, operators will often position technical services fees as a critical investment rather than a discretionary cost, arguing that early involvement can reduce inefficiencies, avoid costly redesigns and support a smoother transition into operation. From an owner’s perspective, the key consideration is therefore not to eliminate overlap, but to ensure that roles are clearly defined and coordinated so that the operator’s input enhances, rather than duplicates, the broader project team’s work.
Relationship to the Management Agreement
Technical services are often documented in a separate agreement or as a distinct schedule within the HMA. While linked to the operator, they are commercially and legally distinct from the ongoing management services.
In some cases, particularly with strong brands, technical services fees may be presented as a standard or non-negotiable component of the overall deal. However, in practice, the level of flexibility can vary significantly depending on market conditions and the project’s strategic importance to the operator.
In more competitive situations, or where a project has particular strategic importance to the operator, the parties may negotiate a reduction, waiver, deferral, or offset of technical services fees. Where an upfront payment is offset against future incentive fees, the owner should assess when those credits become available, any conditions or limits on their use, and what happens if sufficient incentive fees never become payable. An offset may reduce the nominal cost over the agreement’s life, but its economic value depends on timing and whether the credits are ultimately realised. The arrangement should therefore be assessed through the project’s cash flow model, alongside the operator’s technical services scope and the wider commercial terms.
From the operator’s perspective, there is also a clear commercial rationale for maintaining a meaningful technical services fee during the development phase. These fees provide early-stage income and help ensure that the operator is compensated for the deployment of its technical resources, particularly if a project is delayed, restructured, or does not proceed to opening. In this sense, technical services fees serve not only as payment for services rendered but also as a mechanism to anchor the relationship, both contractually and financially, during the development process.
Hidden and Overlooked Costs
One of the most common pitfalls in evaluating hotel management fees is focusing solely on headline percentages while overlooking the broader cost structure. Reimbursable expenses, in particular, can vary significantly and may not always be subject to the same level of scrutiny as core fees. The allocation of centralised costs across multiple properties can also be opaque, making it difficult to assess whether the charges are proportionate.
There is also potential for overlap between different fee categories, particularly in structures where brand and management functions are separated. Without careful coordination, this can result in cost duplication.
A comprehensive understanding of all fee components, including less visible ones, is essential for accurately assessing the economic impact of an HMA. This is also a strong reason to engage a qualified hotel consultant as part of the process. While legal advisors may identify and document the existence of these fee provisions, the interpretation, practical application and financial impact of such items require a detailed understanding of hotel operations and market practice.
In particular, the interrogation of operator charges and underlying cost assumptions often requires specialist expertise, as these are not always presented in a fully transparent or easily comparable manner. A knowledgeable consultant can therefore play a critical role in analysing, benchmarking and challenging these costs to ensure that the overall fee structure is properly understood and commercially balanced.
Fee Structuring Strategies (Owner Perspective)
From an owner’s perspective, the objective is to structure fees in a way that supports long-term asset performance while providing commercially sustainable remuneration for the operator. A lower revenue-based fee may reduce charges during weaker trading periods, but any corresponding increase in incentive fees must be assessed against the agreed profit definition and payment conditions. For leveraged projects in particular, alternative structures should be tested against the same revenue, operating cost, and financing assumptions to establish how much cash remains for debt service, capital requirements, and investor returns. The preferred arrangement should reflect the project’s risk profile and expected trading pattern, alongside the operator’s contribution and commercial requirements.
Early-year fee reductions can also play an important role, particularly in new developments where ramp-up periods can place pressure on cash flow. Clear and precise definitions of revenue and profit metrics are essential to avoid disputes and ensure transparency. Ultimately, effective fee structuring is about achieving alignment. The operator should be incentivised to maximise performance, while the owner retains sufficient control over costs and cash flow.
How Operators Evaluate Fees
Operators evaluate fee structures not only in terms of percentages but in terms of total expected income over the life of the agreement. The projected fee income for a stabilised year is a key metric for internal decision-making, and in many cases, this stabilised fee income, expressed in absolute monetary terms, serves as a minimum threshold for determining whether a project is of interest. If the anticipated fee level does not meet internal benchmarks, the project is unlikely to proceed regardless of other qualitative merits.
This evaluation is typically undertaken by internal feasibility or development analysis teams, which operate separately from the development directors with whom owners usually engage. While development teams may express strong interest in a project, final approval is often subject to internal underwriting processes that assess projected fee income, market positioning, operational complexity and risk exposure. As a result, fee structures must satisfy not only commercial negotiation but also internal approval criteria that may sit beyond the immediate control of the counterparties at the negotiating table.
At a broader level, operators will assess the total economic value of the contract, often on a net present value (NPV) basis, taking into account the full duration of the agreement and the expected timing of fee income. In this sense, the management contract represents a long-term income stream that contributes to the operator’s overall portfolio value and, in some cases, forms part of how the business is evaluated at a corporate level.
Understanding how operators assess fees, both at a stabilised-year level and across the life of the contract, can provide valuable insights during negotiations, helping owners structure proposals that are not only commercially competitive but also capable of meeting internal operator thresholds.
Common Mistakes When Negotiating Hotel Management Fees
A common mistake in fee negotiations is focusing solely on reducing the base fee without considering the broader fee structure. This can lead to unintended consequences, such as higher incentive fees or increased system charges.
Another frequent issue is overcomplicating incentive structures. While complex models may appear attractive, they can be difficult to manage and may not deliver the intended alignment.
Finally, failing to account for the full range of operator-related costs can result in a significant underestimation of the total financial impact. A holistic approach is essential to ensure that all elements of the fee structure are properly understood and evaluated.
Owner’s Checklist for Comparing Hotel Management Fees
Before agreeing commercial terms, request a complete fee schedule and compare operator proposals using the same financial assumptions. This allows developers and investors to distinguish differences in headline rates from differences in calculation bases, payment conditions, and additional charges. The comparison should cover the opening period, stabilised operations, and a downside scenario, with attention to both operator remuneration and the cash remaining for the owner.
| Review area | Questions for the owner |
|---|---|
| Revenue definition | Which income streams are included in the base fee calculation, and which are excluded? |
| Incentive fee calculation | What profit measure applies, which deductions are permitted, and are higher rates applied to the whole calculation base or only to incremental bands? |
| Payment conditions | Are fees subject to an owner’s priority return, thresholds, deferral arrangements, or subsequent reconciliation? |
| Additional charges | What reservation, marketing, loyalty, technology, central service, and reimbursable costs apply? |
| Future changes | How can charges change, what notice is required, and what approval or challenge rights does the owner retain? |
| Development and opening | What technical services and pre-opening fees apply, what do they cover, and are any credits or offsets conditional? |
| Owner cash flow | After all fees and other project obligations, how much cash remains under each trading scenario? |
Evaluating Hotel Management Fees as an Owner
Hotel management fees are not simply a set of percentages applied to revenue and profit. They form a central component of the commercial relationship between the owner and the operator, shaping how value is created, allocated, and sustained over the life of the asset.
A well-structured fee arrangement aligns incentives, supports financial performance and reflects both market conditions and the specific characteristics of the project. Conversely, a poorly structured model can erode profitability, distort operational priorities and create long-term misalignment between the parties.
For developers, investors and asset managers, the focus should therefore extend beyond individual fee levels to the overall structure, interaction and long-term impact of the fee framework. A clear understanding of how these components work together is essential, not just to negotiate effectively, but to protect value over the duration of the investment.
Illustrative Fee Clauses and Drafting Considerations
The structure and impact of hotel management fees are ultimately determined by how they are defined and documented within the agreement. While each contract is negotiated individually, certain fee-related provisions require particular clarity due to their long-term financial implications. The following illustrative clauses are provided as examples of how key concepts may be addressed in practice. They are not intended as standard templates, but rather as guidance to highlight areas where careful drafting and commercial alignment are essential.
1. Base Fee Definition Clause
Purpose: To define the basis on which the operator’s core fee is calculated and to clearly establish the scope of revenue included in that calculation.
Sample Clause (Illustrative):
“The Base Fee shall be calculated as [X]% of Total Hotel Revenue for each Accounting Period. ‘Total Hotel Revenue’ shall include all revenue derived from the operation of the Hotel, excluding VAT and excluding revenue generated from separately operated third-party facilities as defined in Schedule [●].”
Sample Clause Ramped (Illustrative):
“The Base Fee shall be calculated as a percentage of Total Hotel Revenue for each Accounting Period, applied on a ramp-up basis as follows: (i) [1.5]% for the first full Fiscal Year following the Opening Date; (ii) [2.0]% for the second full Fiscal Year; (iii) [2.5]% for the third full Fiscal Year; and (iv) [3.0]% for each Fiscal Year thereafter. For the avoidance of doubt, any partial Fiscal Year in which the Opening Date occurs shall be excluded from the ramp-up period, and the applicable fee for such period shall be [●]%. ‘Total Hotel Revenue’ shall be defined in accordance with Schedule [●] of this Agreement.”
The definition of Total Hotel Revenue is critical. Particular attention should be given to mixed-use elements and third-party-operated areas to avoid the unintended inclusion of revenue streams not directly managed by the operator. This is particularly important in mixed-use developments, resort environments and assets with leased outlets, where the boundary between hotel and non-hotel income can materially affect fee calculations.
2. Incentive Fee: Whole-Base Scaled Structure
Purpose: To align the operator’s remuneration with the profitability of the hotel through a performance-based fee structure.
The following example illustrates a whole-base structure: the achieved GOP margin determines a single fee rate applied to the entire agreed GOP base. It does not illustrate marginal banding. As explained under “Structures and Variations,” this approach can produce a substantial change in the incentive fee when profitability crosses a threshold. The example should be read alongside that comparison and the discussion of provisional calculations and year-end reconciliation.
Sample Clause (Illustrative):
“The Incentive Fee shall be calculated on Gross Operating Profit (GOP) for each Accounting Period as follows: (i) 0% of GOP where GOP margin is below [20%]; (ii) [7]% of GOP where GOP margin is between [20%] and [40%]; and (iii) [10]% of GOP where GOP margin exceeds [40%].”
In the operator templates discussed here, this wording is generally understood to apply the rate associated with the achieved GOP margin to the entire agreed GOP base, rather than to incremental bands. However, the clause does not expressly state that distinction. A worked calculation or financial model may be included in a schedule, annex, or addendum to the agreement, illustrating how the fee is intended to operate.
Owners should review that material alongside the clause, confirm that both produce consistent results, and check the calculation immediately below, at, and above each threshold. Where no worked example is provided, one should be requested. Also check the definitions of GOP and revenue, the assessment period, and the provisions for provisional payments and final reconciliation elsewhere in the agreement.
The selection of thresholds and percentages should reflect the hotel’s operating characteristics and realistic performance expectations, including the opening and stabilisation period. Owners should assess whether targets remain meaningful under different trading conditions and whether the resulting fee movements support the intended commercial balance. A scaled structure should be evaluated through its actual financial outcomes, including threshold effects and year-end adjustments, rather than assumed to create alignment simply because the fee percentage increases with profitability.
3. AGOP Adjustment Clause
Purpose: To define how Gross Operating Profit is adjusted for the purpose of calculating the incentive fee.
Sample Clause (Illustrative):
“For the purposes of calculating Adjusted Gross Operating Profit (AGOP), the following items shall be deducted from GOP: (i) Base Fee, (ii) FF&E Reserve contributions, (iii) property insurance costs, and (iv) such other agreed deductions as set out in Schedule [●]. No additional deductions shall be applied without prior written agreement.”
The definition of AGOP can significantly impact fee outcomes. It is generally advisable to clearly define permitted deductions and limit the scope for future adjustments, while ensuring that the agreed structure remains practical and aligned with the intended commercial framework. This is most critical in leveraged projects or where investor return thresholds are tight, as small adjustments to AGOP can materially affect distributable cash flow.
Closing Note
These examples illustrate how relatively small drafting differences can translate into significant financial outcomes over the life of an agreement. Careful attention to fee-related provisions is therefore essential to ensure that the intended commercial balance is achieved in practice.
The content presented on this page is for general informational purposes only and does not constitute legal, financial or investment advice. Hotel management fee structures and related contractual provisions are highly variable and should be assessed on a case-by-case basis.
No representation or warranty is made as to the completeness or accuracy of the information, and no liability is accepted for any reliance placed upon it. Any decisions relating to hotel development, investment or contractual arrangements should be made in consultation with appropriately qualified professional advisors.
Further resources:
See HDG – Hotel Contract Lawyer Contacts
See HDG – Hotel Operator Links
See HDG – Links to Hotel Consultants
Hospitality Net (April 2024) – “A New Approach to Hotel Management Fees“
Disclaimer: This page provides general information and does not constitute legal, tax or financial advice. Contract terms and applicable laws vary by agreement and jurisdiction. Owners and developers should obtain independent professional advice before entering into an agreement or proceeding with a transaction.
For further perspectives on hotel development and investment, follow Darren Blanchard on LinkedIn. Questions and practical observations from developers, investors, owners, and educators are welcome.